Introduction: Why Passive Components Matter More Than Ever
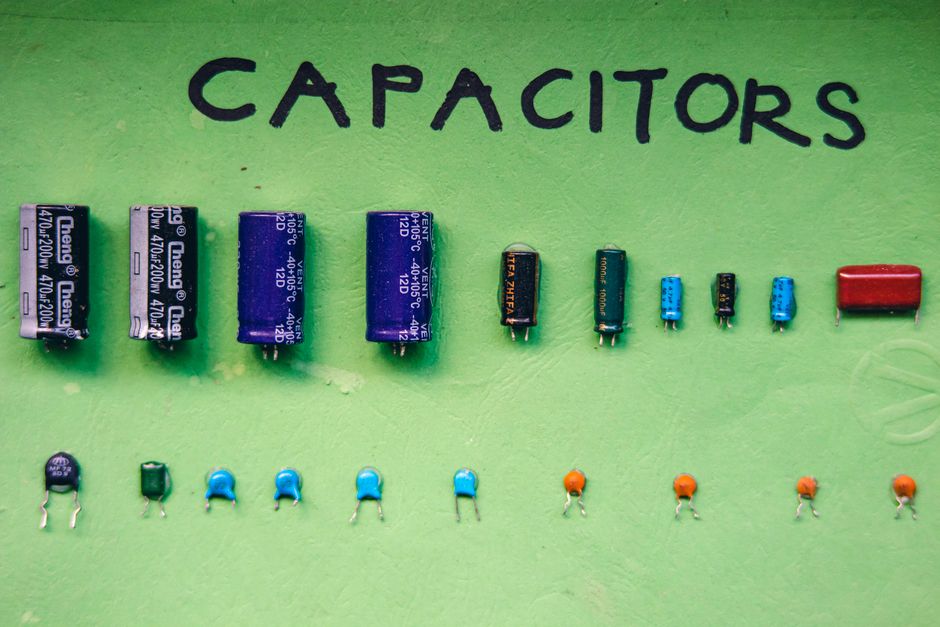
Passive electronic components — resistors, capacitors, inductors, and their close relatives — rarely grab headlines the way advanced processors or AI accelerators do. Yet every active chip in existence depends on them. A single electric vehicle can contain more than 10,000 passive components. A 5G base station may use tens of thousands. As the electronics industry races toward electrification, automation, and ubiquitous connectivity, the passive components market has quietly become one of the most strategically important segments of the global supply chain.
In this guide, we break down the latest market news, emerging trends, pricing dynamics, and practical sourcing strategies for engineers, procurement managers, and distributors who work with passive components every day.
Market Overview: Size, Growth, and Key Drivers
The global passive components market was valued at roughly USD 40 billion in the mid-2020s and is projected to grow at a compound annual growth rate (CAGR) of approximately 5–7% through the end of the decade. While that growth rate may look modest compared with semiconductors, the passive sector is characterized by enormous unit volumes, long product lifecycles, and deep entrenchment in virtually every electronic system.
Primary Demand Drivers
- Electrification of transport: EVs and hybrids use far more passives per vehicle than internal combustion models, particularly high-voltage capacitors and power inductors.
- 5G and 6G infrastructure: Dense RF front-ends require precision capacitors, inductors, and filters.
- Industrial automation and IoT: Sensors, controllers, and edge devices all need reliable passives in compact packages.
- Renewable energy: Solar inverters, wind converters, and battery management systems rely heavily on film and electrolytic capacitors.
- Consumer electronics: Smartphones, wearables, and smart home devices continue to drive miniaturized MLCC demand.
Regional Production Landscape
Japan, South Korea, Taiwan, and China dominate passive component manufacturing. Companies such as Murata, TDK, Taiyo Yuden, Yageo, Samsung Electro-Mechanics, and Vishay control large shares of the MLCC, resistor, and inductor markets. Recent years have seen significant capacity expansion in Southeast Asia — particularly Vietnam, Malaysia, and the Philippines — as manufacturers diversify away from single-region dependence.
Key Trends Shaping the Passive Components Industry
1. Miniaturization Without Performance Loss
Space-constrained designs continue to push package sizes downward. The 0201 (0.6 mm × 0.3 mm) and even 01005 (0.4 mm × 0.2 mm) form factors are now common in high-density boards. Manufacturers are also improving volumetric efficiency, meaning smaller parts deliver capacitance and power ratings that previously required larger packages. For designers, this means re-evaluating land patterns, solder paste deposition, and pick-and-place capabilities.
2. High-Temperature and High-Voltage Ratings
Automotive and industrial applications demand components rated for 150°C or higher, along with robust voltage derating margins. AEC-Q200 qualification has become a baseline requirement for automotive-grade passives. Suppliers are introducing new dielectric formulations and construction techniques to meet these demands while maintaining reliability over 15–20 year service lives.
3. Supply Chain Regionalization
The pandemic-era shortages taught the industry a hard lesson about concentration risk. OEMs and EMS providers are now dual-sourcing and, in some cases, multi-sourcing passive components across regions. Distributors are holding larger buffer inventories of critical part numbers, and design engineers are increasingly specifying pin-compatible alternatives from multiple vendors during the design phase.
4. Sustainability and Material Innovation
Regulatory pressure and corporate ESG goals are driving interest in lead-free, halogen-free, and recyclable component constructions. Some manufacturers are also exploring bio-based dielectrics and reduced rare-earth content in inductors. While performance parity remains the priority, sustainability credentials are becoming a differentiator in tenders and supplier scorecards.
5. Pricing Pressure and Commoditization
After the severe shortages of 2021–2022, capacity additions have brought many commodity passives back into balance or oversupply. Standard 0402 and 0603 MLCCs, chip resistors, and general-purpose inductors have seen price erosion. However, specialty parts — high-voltage MLCCs, precision thin-film resistors, and high-current power inductors — remain tighter and command premium pricing.
Segment-by-Segment Analysis
| Segment | Typical Applications | Market Trend |
|---|
| MLCCs (Multilayer Ceramic Capacitors) | Decoupling, filtering, RF matching | Miniaturization, high-capacitance density, automotive growth |
| Aluminum Electrolytic Capacitors | Power supplies, motor drives, inverters | Shift to polymer and hybrid types for longer life |
| Film Capacitors | EV powertrains, renewable energy, snubbers | Steady growth tied to electrification |
| Chip Resistors | Signal conditioning, current sensing, pull-ups | Commodity pricing, growth in precision variants |
| Inductors and Chokes | DC-DC conversion, EMI suppression, power delivery | Strong demand for high-current, low-DCR parts |
| Ferrite Beads and Filters | EMI/EMC compliance, high-speed interfaces | Growth in automotive and data center applications |
Practical Tips for Engineers and Procurement Teams
Design for Availability
- Standardize where possible: Using common package sizes and values reduces the number of unique part numbers and improves negotiating leverage.
- Qualify alternates early: Identify at least two approved sources for every critical passive component during the design phase.
- Check lifecycle status: Avoid specifying parts nearing end-of-life, even if they are currently cheap and available.
Sourcing and Inventory Strategy
- Monitor lead times monthly: Lead times for specialty passives can stretch from weeks to many months with little warning.
- Use authorized distribution: Gray-market passives carry counterfeit and out-of-spec risks that can devastate production yields.
- Build strategic buffers: For long-lead or single-source parts, maintaining 8–12 weeks of buffer stock is often cheaper than expediting or redesigning.
Testing and Verification
- Perform incoming inspection on critical lots, including capacitance, ESR, and DC resistance checks.
- Validate solderability and thermal cycling performance for automotive and industrial builds.
- Keep detailed traceability records to support recalls or field failure analysis.
What to Watch in the Coming Years
Several developments are likely to define the next phase of the passive components market:
- Embedded passives: Embedding capacitors and resistors inside PCB layers can free up surface area and improve electrical performance, though adoption remains niche due to cost and complexity.
- Wide bandgap compatibility: GaN and SiC power stages switch faster and hotter, demanding passives with lower ESL and higher temperature ratings.
- AI-driven demand forecasting: Distributors and manufacturers are investing in analytics to predict demand spikes and avoid the bullwhip effects seen in past cycles.
- Consolidation: Mergers and acquisitions among mid-tier passive manufacturers may continue, reshaping the competitive landscape.
Conclusion: Staying Ahead in a Quietly Critical Market
Passive electronic components may not be glamorous, but they are the connective tissue of modern electronics. Understanding market trends — from miniaturization and automotive qualification to supply chain regionalization and pricing cycles — gives engineers and procurement teams a real competitive advantage. By designing for availability, qualifying multiple sources, and keeping a close eye on lead times and technology shifts, you can keep production running smoothly even when the market tightens.
Whether you are specifying a single decoupling capacitor or managing a global bill of materials, the passive components market deserves a permanent place on your radar.
 English
 简体中文
 Русский
 Español
 Deutsch